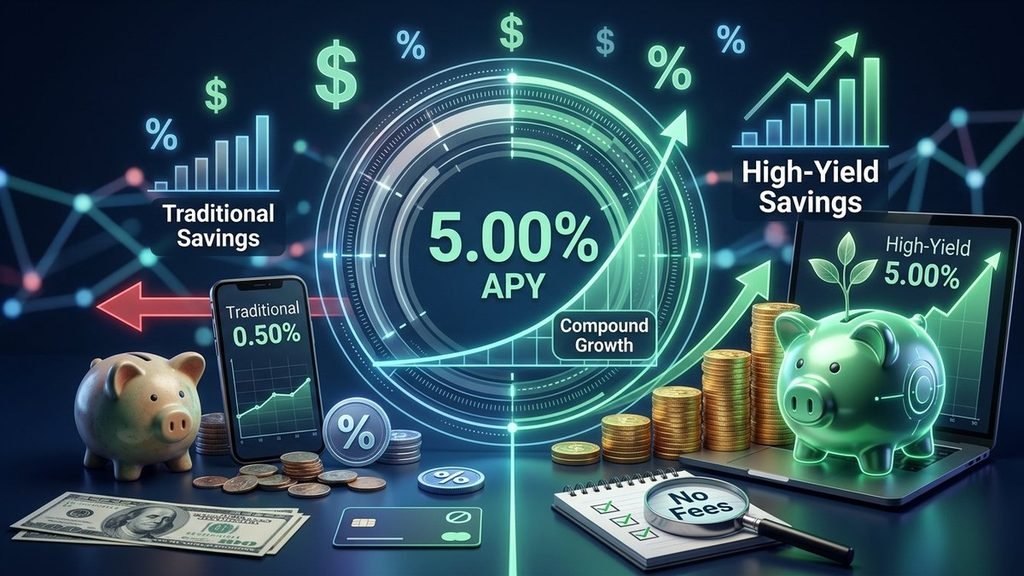
Finding the best high-yield savings accounts can make a meaningful difference in ho your cash gr A regular savings account may provide convenience, but many traditional accounts pay very little interest compared with competitive online savings accounts. A high-yield savings account, often called a HAYS, can offer a much more attractive annual percentage yield while allowing you to keep your money accessible.
This matters whether you are building an emergency fund, saving for a home, planning a large purchase, setting aside money for taxes, or simply trying to earn more interest on cash that is already sitting in a bank account.
In 2026, the U.S. savings market remains highly competitive. Recent September 2026 comparisons show top high-yield savings accounts offering rates around 4% or more, with certain accounts advertising rates as high as 4.50% under specific conditions. Bank rate’s September 30 comparison, for example, listed Happen Bank and Western State Bank at 4.20% PAY, CIT Bank at 4.10%, Viol Bank at 4.01%, and Live Oak Bank at 4.00%.
However, the account with the highest advertised PAY is not automatically the right choice for every saver.
Some accounts have balance limits, direct-deposit requirements, minimum deposits, promotional rates, or other conditions. Others may offer a slightly lower rate but provide easier transfers, stronger digital banking tools, fewer restrictions, or no minimum balance.
The goal of this guide is to explain how to compare the best high-yield savings accounts in 2026, understand Apes, evaluate account features, calculate potential interest earnings, and choose an account that fits your financial goals.
What Is a High-Yield Savings Account?
A high-yield savings account is a savings account that generally pays a higher interest rate than a conventional savings account.
The basic concept is simple. You deposit money with a bank, and the bank pays you interest for keeping your funds there.
That interest is usually expressed as an annual percentage yield, or PAY.
For example, if you place $10,000 in a savings account earning a 4.00% PAY and the rate remains unchanged for a full year, your interest earnings could be roughly $400 before taxes, assuming your balance does not change.
The exact amount can differ because Apes are affected by compounding and because savings-account rates can change.
A HAYS can be particularly useful for money that needs to remain relatively liquid.
You might use one for:
- Emergency savings
- A home down payment
- Car savings
- Vacation savings
- Business reserves
- Tax savings
- Short-term financial goals
- A cash reserve for unexpected expenses
The main attraction is the combination of interest, accessibility, and relatively low volatility compared with investments such as stocks.
Why High-Yield Savings Accounts Are Popular
The difference between a traditional savings account and a high-yield savings account can be surprisingly large.
The national average savings rate remains far below the best high-yield offers available in the market. September 2026 comparisons show that top savings accounts can offer rates several percentage points above ordinary savings products.
That difference can translate into hundreds or even thousands of dollars over time.
Imagine that you have $50,000 in savings.
At a hypothetical 0.50% PAY, the annual interest would be roughly $250.
At 4.00% PAY, the annual interest would be roughly $2,000.
The difference would be about $1,750 in one year, before taxes and assuming both rates remain unchanged.
This is why comparing savings accounts matters more as your balance increases.
What Does PAY Mean?
PAY stands for Annual Percentage Yield.
It is designed to show how much you can earn from a deposit over one year while accounting for the effect of compounding.
When comparing savings accounts, PAY is usually more useful than simply looking at the stated interest rate.
For example:
Account A: 3.50% PAY
Account B: 4.00% PAY
Assuming the terms are otherwise identical, Account B provides the higher annual yield.
However, the terms may not actually be identical.
The 4.00% account could require a qualifying direct deposit.
The 3.50% account might have no requirements at all.
The higher rate could apply only up to a certain balance.
The lower rate could apply to the entire balance.
That means PAY is important, but the complete account agreement is even more important.
How High-Yield Savings Rates Work
High-yield savings rates are generally variable.
That means the bank can increase or decrease the PAY over time.
The broader interest-rate environment is one factor that influences deposit rates.
The Federal Reserve’s September 2026 decision moved the federal-funds target range to 3.75% to 4.00%.
Banks do not necessarily change savings rates immediately or by the same amount as the Federal Reserve. Each institution considers its funding needs, competition, profitability, customer base, and other factors.
This is why one bank may offer a materially different savings rate from another bank even when both operate under the same general interest-rate environment.
For consumers, that means a competitive savings rate is something you should review periodically.
Best High-Yield Savings Accounts in 2026
There is no single bank that is universally the best high-yield savings account for every consumer.
Instead, different accounts may be suitable for different situations.
Some current September 2026 comparisons include the following providers and products among competitive savings options:
Happen Bank
Bank rate’s September 30, 2026 comparison listed Happen Bank’s savings account at 4.20% PAY with no minimum deposit.
An account like this can appeal to savers who want a competitive rate without having to deposit a large amount just to open the account.
However, the PAY should always be verified directly before opening an account because variable rates can change.
Consumers should also review the bank’s current terms, fees, transfer policies, and eligibility requirements.
Western State Bank
Bank rate also listed Western State Bank at 4.20% PAY with a $1,000 minimum deposit in its September 2026 comparison.
This illustrates an important point about comparing .
Two accounts can have similar Apes but different entry requirements.
If you already have more than $1,000 available for savings, the minimum may not matter.
For someone just beginning to build an emergency fund, it could be more important.
CIT Bank
Bank rate listed CIT Bank at 4.10% PAY with a $100 minimum deposit in its September 2026 comparison.
CIT Bank is an example of why consumers should compare both interest rates and minimum-deposit requirements.
An account paying slightly less than the market leader can still be attractive if its requirements are straightforward.
Viol Bank
Viol Bank was listed at 4.01% PAY with a $100 minimum deposit in Bank rate’s September 2026 comparison.
A competitive rate around 4% may be useful for savers who want to keep emergency funds productive without exposing the money to market fluctuations.
Live Oak Bank
Bank rate listed Live Oak Bank at 4.00% PAY with no minimum deposit in its September 2026 comparison.
An account without a minimum deposit requirement can be useful for people who are starting small and plan to build their balance gradually.
GO2bank
Some September 2026 comparisons reported GO2bank offering up to 4.50% PAY on qualifying savings balances up to $5,000 under certain conditions.
This is a good example of why the phrase “up to” matters.
An advertised maximum rate may not apply to every dollar in the account or to every customer automatically.
Before opening a high-yield savings account, determine:
- What balance receives the headline PAY
- Whether a checking relationship is required
- Whether direct deposit is required
- Whether the rate is promotional
- What rate applies after the promotion
- Whether fees reduce the benefit
The actual value of an account depends on the terms that apply to your situation.
Why the Highest PAY Is Not Always the Best Choice
Suppose one account advertises 4.50% PAY and another offers 4.00%.
At first glance, the 4.50% account looks better.
But imagine the 4.50% rate applies only to the first $5,000, while the 4.00% account applies to your entire $50,000 balance.
The second account may generate more total interest.
Or imagine the 4.50% account requires direct deposits that you cannot easily satisfy.
A simple 4.00% account with no requirements may be more convenient.
This is why smart savings decisions require looking beyond the headline percentage.
How Much Can You Earn at 4% PAY?
Let’s use a simplified example.
$1,000 at 4%
Approximately $40 per year.
$5,000 at 4%
Approximately $200 per year.
$10,000 at 4%
Approximately $400 per year.
$25,000 at 4%
Approximately $1,000 per year.
$50,000 at 4%
Approximately $2,000 per year.
$100,000 at 4%
Approximately $4,000 per year.
These figures are estimates rather than guarantees.
Actual earnings depend on PAY changes, account balance, deposits, withdrawals, and interest-compounding practices.
Still, they demonstrate why even a small rate difference becomes increasingly important as your savings grow.
What If the PAY Is 4.50%?
At a hypothetical 4.50% PAY:
$5,000 could earn roughly $225 in one year.
$10,000 could earn roughly $450.
$25,000 could earn roughly $1,125.
$50,000 could earn roughly $2,250.
$100,000 could earn roughly $4,500.
Again, these calculations assume the rate remains unchanged throughout the year.
If the rate is promotional, conditional, or variable, actual results can differ.
Why Compounding Matters
Interest can be compounded, which means the interest you earn can become part of the balance that earns future interest.
For example, suppose you start with $10,000.
You earn interest during the year.
Your balance increases.
The larger balance can then generate additional interest.
Compounding becomes more noticeable over longer periods.
However, because HAYS Apes can change, you should not assume that today’s interest rate will stay fixed for ten years.
High-Yield Savings Accounts and Inflation
Inflation is another reason people compare savings rates.
If the price of goods and services rises over time, the purchasing power of cash can decrease.
Suppose your savings account earns 4% while inflation is 3%.
The nominal balance is growing by 4%, but the purchasing-power gain is much smaller.
If inflation were 5% while your savings account earned 4%, your purchasing power could still decline even though your bank balance increased.
This is why a HAYS is generally best viewed as a cash-management tool, not a complete long-term investment strategy.
Best Uses for a High-Yield Savings Account
High-yield savings accounts are particularly useful for money you need to preserve and access.
Emergency Funds
An emergency fund is one of the most common uses.
You might use it for:
- Unexpected medical expenses
- Car repairs
- Home repairs
- Job loss
- Emergency travel
- Insurance deductibles
- Essential bills during an income disruption
Home Down Payment
If you are saving for a home, you may want the money accessible and relatively stable.
A HAYS can provide interest while you continue accumulating the down payment.
Car Purchase
You can create a dedicated car fund and automatically transfer money into the account every month.
Vacation Savings
Separating vacation money from your checking account can make the spending plan clearer.
Tax Savings
Freelancers and self-employed individuals may use savings accounts to separate money reserved for taxes.
Business Reserves
A business may keep cash reserves for payroll, taxes, equipment, emergencies, or seasonal fluctuations.
How Much Should Your Emergency Fund Be?
There is no universal answer.
A commonly used framework is several months of essential living expenses.
For example, if your essential monthly spending is $3,000:
Three months = $9,000
Six months = $18,000
Nine months = $27,000
However, your actual target depends on your circumstances.
Consider:
- Income stability
- Household size
- Employment security
- Insurance coverage
- Debt payments
- Housing costs
- Medical expenses
- Availability of other resources
A household with highly predictable dual incomes may choose a different emergency-fund target from a household dependent on one variable income.
How to Build an Emergency Fund Faster
The most effective strategy is usually automation.
Set an automatic transfer from checking to savings after each paycheck.
For example:
$100 per month
$250 per month
$500 per month
$1,000 per month
The amount should be realistic enough to maintain consistently.
A smaller contribution made every month is often more useful than an unrealistic savings target that causes you to stop contributing.
Should You Keep Your Emergency Fund in Checking?
Checking accounts are designed for everyday spending.
They are useful for:
- Rent
- Utilities
- Credit-card payments
- Groceries
- Debit-card purchases
- Direct deposits
But checking accounts may pay little or no interest.
Keeping your entire emergency fund in checking can therefore mean giving up potential interest.
A common structure is to maintain enough checking money for short-term bills and move emergency savings into a separate high-yield savings account.
Should You Keep Your Emergency Fund in Cash at Home?
Cash at home does not earn interest and may face risks such as theft, loss, or physical damage.
Some people keep a small amount of physical cash for emergencies, but larger emergency reserves are generally easier to manage through secure financial accounts.
An insured savings account also provides protections that physical cash cannot provide.
Are High-Yield Savings Accounts Safe?
A high-yield savings account at an FDIC-insured bank can offer substantial deposit protection within applicable insurance limits.
The FDIC’s standard coverage is $250,000 per depositor, per insured bank, for each ownership category.
The important phrase is “per insured bank” and “ownership category.”
If you have more than $250,000, you need to understand how your deposits are structured.
FDIC insurance also covers eligible deposits, not all financial products.
FDIC Insurance Explained
The FDIC protects eligible deposits at insured banks.
Examples of commonly insured deposit products include:
- Savings accounts
- Checking accounts
- Certificates of deposit
- Money market deposit accounts
The standard limit is $250,000 per depositor, per insured bank, per ownership category.
For example, a qualifying individual savings account with $200,000 at one insured bank would generally remain below the standard single-account insurance limit.
But multiple accounts in the same ownership category at the same institution do not automatically create unlimited coverage.
What Happens if You Have More Than $250,000?
Suppose you have $400,000 in cash.
Putting the entire amount into a single ownership category at one insured bank could leave a portion above the standard insurance limit.
The FDIC has different rules for different ownership categories, and certain categories can receive separate coverage.
People with substantial cash balances should review official FDIC guidance or consult a qualified professional before assuming their entire balance is protected.
What About Credit Unions?
Credit unions use a different federal insurance system.
Federally insured credit unions can be insured by the National Credit Union Administration, or NCUA.
This means consumers comparing bank savings accounts and credit-union savings products should verify the applicable insurance agency and limits.
The basic principle is the same:
Know who insures your deposit and how much is covered.
High-Yield Savings Account vs CD
A certificate of deposit is another popular place to keep cash.
A key difference is that a CD generally has a fixed term.
For example:
6 months
12 months
24 months
36 months
During that period, you may receive a fixed interest rate.
If you withdraw money before maturity, an early withdrawal penalty may apply.
A HAYS usually provides greater flexibility because it does not require the same fixed maturity commitment.
As of September 2026, top CD yields remain competitive with savings products, making CD comparisons relevant for savers who do not need immediate access to their money.
High-Yield Savings Account vs Money Market Account
A money market account is a deposit account that can provide some features associated with checking accounts.
Depending on the institution, it may provide:
- Debit-card access
- Check writing
- ATM access
- Competitive interest
A HAYS may provide a higher yield, especially among online institutions.
Money market accounts can be useful for consumers who want more transaction flexibility.
Compare both based on actual account terms rather than the account name.
High-Yield Savings Account vs Money Market Fund
A money market deposit account is not the same thing as a money market mutual fund.
This distinction is important.
A money market deposit account at an insured bank may qualify for FDIC insurance.
A money market mutual fund is an investment product and is not FDIC-insured.
Do not assume the word “money market” automatically means your money has deposit insurance.
High-Yield Savings Account vs Stocks
Stocks can potentially produce higher long-term returns, but stock values can fall sharply.
A savings account is designed for stability and liquidity.
If you need your emergency fund next month, you may not want the value of that money dependent on stock-market conditions.
On the other hand, retirement savings intended for decades in the future may require a more growth-oriented strategy.
The right account depends on your time horizon.
High-Yield Savings Account vs Emfs
Exchange-traded funds can provide exposure to stocks, bonds, commodities, or other assets.
They are useful investment vehicles but are not substitutes for an emergency savings account.
The value of an ETC can fluctuate.
A HAYS provides a more predictable cash balance, although the interest rate itself can change.
A balanced financial plan may use both savings accounts and investments for different purposes.
High-Yield Savings Account vs Treasury Bills
Treasury bills are short-term U.S. government securities.
They can be an alternative to savings accounts for certain investors, especially when comparing short-term yields and tax considerations.
However, Treasury bills work differently from bank savings accounts.
They may require purchasing securities and understanding maturity dates, settlement, and brokerage or TreasuryDirect procedures.
A HAYS can be simpler for someone who wants straightforward banking and easy transfers.
How to Choose the Best HAYS for You
The right account depends on what matters most to you.
Ask these questions:
Do you need branch access?
If yes, an online-only bank may be less convenient.
Do you need a minimum opening balance?
If no, look for no-minimum accounts.
Do you receive direct deposit?
If yes, accounts with direct-deposit requirements may be practical.
How much are you depositing?
Large balances make PAY differences more significant.
Do you need ATM access?
Some online savings accounts do not provide it.
Will you need frequent transfers?
Then transfer speed and limits become important.
Is the money for an emergency?
Prioritize accessibility and insurance.
Is the money for a future purchase?
You may be able to compare HAYS rates with CD rates.
What Fees Should You Watch For?
A high PAY does not automatically mean low fees.
Look for:
- Monthly maintenance fees
- Excess withdrawal fees
- Wire-transfer fees
- Returned deposit fees
- Paper statement fees
- Out-of-network ATM fees
- Account closure fees
- Minimum-balance penalties
Some banks have very few fees, but you should always read the current fee schedule.
How Monthly Fees Affect Your Real Return
Suppose your account earns $30 of interest in one month.
Now suppose the account charges a $10 monthly service fee.
Your net gain before taxes is effectively $20.
Over a full year, $10 per month equals $120.
A seemingly competitive savings account can therefore become less attractive if recurring fees are significant.
What Are Balance Requirements?
Some accounts require you to maintain a minimum balance.
For example, the bank may say:
“Earn the advertised PAY with a $1,000 minimum balance.”
If your balance drops below that amount, the rate or account benefits may change.
Other accounts may have no minimum balance.
For beginners, accounts with fewer requirements can be easier to manage.
What Are Balance Caps?
A bank may offer a high PAY only on a limited portion of your savings.
For example:
4.50% on the first $5,000
1.00% on the amount above $5,000
For a customer with $50,000, the headline rate does not describe the entire balance.
Always calculate the effective yield on your actual balance.
What Are Direct Deposit Requirements?
A direct deposit is generally an electronic payment from an employer, government agency, or another qualifying source.
Some high-yield accounts require you to maintain direct deposit to earn the maximum PAY.
If your paycheck is already going into that bank, the requirement may be easy.
If not, you should compare the extra interest with the inconvenience of moving your banking relationship.
What Are Promotional Rates?
Promotional rates are temporary offers designed to attract new customers or deposits.
Before accepting a promotion, determine:
- Start date
- End date
- Required balance
- Eligibility
- Ongoing PAY after the promotion
A temporary 5% rate may be less valuable than a consistent 4% rate if the promotion ends quickly and the ongoing rate is poor.
How Often Do Savings Rates Change?
There is no fixed schedule.
Banks can change variable Apes based on market conditions and their own pricing strategy.
The Federal Reserve’s benchmark rate is influential, but the relationship is not one-to-one.
When the Fed changes rates, some banks adjust their savings rates quickly, while others move more slowly.
That means savers should periodically check their accounts.
Should You Switch Banks for a Higher PAY?
Sometimes.
But switching every few weeks may not be useful.
Suppose your current rate is 4.00% and another bank offers 4.05%.
On $10,000, the difference is only about $5 per year.
It may not be worth the paperwork.
But if your bank pays 1.00% and another insured account pays 4.00%, the difference is much larger.
On $50,000, that gap could represent approximately $1,500 per year before taxes if the rates stayed unchanged.
The larger the difference and balance, the more meaningful the decision becomes.
How to Calculate Whether Switching Is Worth It
Use this simple formula:
Annual Interest Difference = Balance × PAY Difference
Suppose:
Balance = $25,000
Current PAY = 2.00%
New PAY = 4.00%
Difference = 2 percentage points
$25,000 × 0.02 = $500
So the potential annual difference is roughly $500.
Then consider fees, transfer restrictions, and other conditions.
How to Make the Most of a High-Yield Savings Account
A HAYS works best when combined with strong savings habits.
Automate Deposits
Set recurring transfers.
Avoid Unnecessary Withdrawals
Let the balance build.
Review the PAY Periodically
Do not assume the rate stays competitive forever.
Keep Goals Separate
Use buckets or separate accounts when helpful.
Monitor Fees
Make sure fees do not reduce your earnings.
Maintain Emergency Liquidity
Do not lock emergency funds into products you cannot easily access.
How to Save $10,000
Suppose your goal is $10,000.
At $250 per month:
40 months of contributions.
At $500 per month:
20 months.
At $750 per month:
Approximately 13.3 months.
At $1,000 per month:
10 months.
Interest from your HAYS can add to the balance.
The exact timeline will depend on the PAY and when contributions are made.
How to Save $25,000
At $500 per month:
50 months of contributions.
At $1,000 per month:
25 months.
At $2,000 per month:
12.5 months.
Again, interest can shorten the amount of time required slightly, but savings contributions remain the primary driver.
Why Consistent Saving Beats Rate Chasing
Suppose Saver A contributes $500 every month at 3.75%.
Saver B contributes $100 every month at 4.25%.
Saver B has the higher PAY.
But Saver A is putting five times as much into the account every month.
This demonstrates why the savings rate itself matters.
You should optimize both:
- How much you save
- Where you keep it
A strong PAY cannot replace consistent contributions.
Can a HAYS Help With a Down Payment?
Yes.
Home buyers often have several related costs:
- Down payment
- Closing costs
- Inspection
- Moving
- Repairs
- Furniture
- Insurance
- Property taxes
Keeping these funds in a competitive savings account can allow you to earn interest while maintaining liquidity.
If your purchase is only months away, preserving the principal can be more important than pursuing higher market returns.
Can a HAYS Help With College Savings?
It can be useful for short-term education expenses, such as tuition payments due within the next year or two.
However, families saving for college many years in advance may use specialized accounts or investments depending on their situation.
A long-term college strategy should not necessarily be identical to a short-term tuition reserve.
High-Yield Savings for Young Adults
A HAYS can be useful for people building their first emergency fund.
A simple structure might be:
Checking account → everyday expenses
HAYS → emergency savings
Investment account → long-term goals
This helps prevent short-term and long-term money from becoming mixed together.
High-Yield Savings for Families
Families may have multiple short-term expenses.
A HAYS can help create reserves for:
- Medical bills
- Home maintenance
- Car repairs
- School expenses
- Travel
- Holidays
- Insurance deductibles
Separating savings from checking can make budgeting easier.
High-Yield Savings for Freelancers
Freelancers and independent contractors often face irregular income.
A large cash reserve can help smooth out slow months.
Freelancers may also want separate savings for:
- Quarterly taxes
- Business expenses
- Equipment
- Emergency savings
- Health-related costs
- Professional development
A high-yield savings account can provide interest while those funds wait to be used.
High-Yield Savings for Gig Workers
Drivers, delivery workers, creators, and other gig workers can use HYSAs to manage irregular income.
For example, each time you receive income, you could automatically transfer a percentage into savings.
This can create a buffer for periods of lower income.
High-Yield Savings for Small Businesses
Business owners may use savings accounts for cash reserves.
A business could save for:
- Payroll
- Taxes
- Equipment
- Expansion
- Seasonal expenses
- Unexpected repairs
However, business owners should pay attention to the legal ownership of the account and applicable deposit-insurance rules.
Are Savings Account Interest Earnings Taxable?
Generally, interest earned on a regular savings account is taxable income for federal tax purposes.
The financial institution may report interest income using the appropriate tax form when required.
Your actual tax liability depends on your tax situation.
For example, earning $2,000 in interest does not necessarily mean you keep the entire $2,000 after taxes.
Consider the after-tax value when comparing savings products.
How Taxes Affect a 4% PAY
Suppose you earn $1,000 in savings interest.
If your marginal federal tax rate were 24%, the federal tax attributable to that income could be approximately $240 before considering other factors.
Your after-tax amount would therefore be lower than $1,000.
State and local taxes may also apply depending on where you live.
This is one reason comparing financial products using after-tax yield can be useful for some savers.
How to Compare HAYS Rates With CDs
Suppose a HAYS pays 4.00% and a one-year CD pays 4.50%.
The CD offers a higher rate.
But your money is locked up for the CD term, subject to its withdrawal rules.
The HAYS provides more flexibility but may change its PAY.
If you expect to need the money unexpectedly, flexibility may be worth more than the additional 0.50 percentage point.
How to Compare HAYS Rates With Treasury Bills
Treasury bills may also offer competitive short-term yields.
However, T-bills can require more active management.
You need to consider:
- Purchase method
- Maturity date
- Reinvestment
- Liquidity
- Tax treatment
- Brokerage or TreasuryDirect setup
A HAYS is often simpler for everyday cash management.
What Does “No Minimum Balance” Mean?
A no-minimum-balance account generally means you do not need to maintain a specific amount just to keep the account open.
This can be helpful if you are starting with a small emergency fund.
However, “no minimum balance” does not necessarily mean “no fees.”
Read the complete fee schedule.
Why Mobile Banking Matters
Many HYSAs are online-first accounts.
A good mobile application can help you:
- Transfer funds
- Monitor interest
- Create goals
- Lock cards
- Enable security alerts
- Check statements
- Contact customer service
A high PAY is less useful if the digital banking experience is difficult to use.
How to Protect Your Online Savings
Use a unique password.
Enable multi-factor authentication.
Avoid clicking suspicious emails.
Use official bank apps.
Do not share verification codes.
Keep your computer and phone updated.
Review account alerts.
Monitor your statements.
These simple security habits can reduce the risk of unauthorized access.
What Is the Difference Between a HAYS and a Savings Bucket?
Some banks provide “buckets” or “vaults.”
A bucket may allow you to label part of your savings for a specific goal.
For example:
Emergency Fund: $10,000
Vacation: $2,000
Car: $4,000
Home Repair: $3,000
These amounts may remain in one overall savings account while being tracked separately in the banking interface.
This can be useful for organization.
Should You Have More Than One HAYS?
There is no universal need to have multiple accounts.
One account may be enough for simple finances.
Multiple accounts can help when you have very different goals.
For example, you might keep emergency savings separate from a home down-payment fund.
The downside is complexity.
More accounts mean more passwords, statements, transfers, and account details to monitor.
How to Build a Simple Two-Account System
A simple financial system could be:
Checking Account
Use for:
- Bills
- Groceries
- Daily expenses
- Direct deposits
High-Yield Savings Account
Use for:
- Emergency fund
- Major purchases
- Short-term goals
This keeps your savings separate while maintaining easy access.
A Three-Account Strategy
You could also use:
Checking → daily spending
HAYS → emergency and short-term savings
Investment account → long-term growth
This structure can help assign each dollar a purpose.
Best High-Yield Savings Account Features for Large Balances
Large-balance savers should focus on:
- Competitive PAY
- No unnecessary fees
- High or unlimited balance at the advertised rate
- FDIC coverage
- Transfer limits
- Reliable customer service
- Clear ownership structure
For a $200,000 balance, a small rate difference can be significant.
At 4%, $200,000 could generate approximately $8,000 of annual interest if the rate remained unchanged.
At 3%, it would generate roughly $6,000.
That is a $2,000 difference.
Why Deposit Insurance Becomes More Important With Larger Balances
As your balance grows, the standard $250,000 FDIC coverage limit becomes increasingly relevant.
If you have $20,000, the issue is relatively simple.
If you have $300,000, $500,000, or $1 million, account structure matters much more.
The FDIC provides detailed rules based on ownership category and other factors.
Should You Spread Money Across Banks?
Some people with balances above standard insurance limits choose to spread deposits across multiple insured institutions.
This can potentially increase the amount of money covered by deposit insurance.
However, the exact coverage rules depend on ownership categories and institution structure.
Do not assume that opening multiple accounts at the same bank automatically creates separate coverage.
The bank’s legal identity and ownership category matter.
What Is a Variable PAY?
A variable PAY means the bank can change the rate.
This is common with savings accounts.
For example:
January: 4.25%
March: 4.00%
June: 3.75%
These are illustrative figures only.
You should never assume a variable rate is guaranteed.
What Is a Fixed Rate?
A fixed rate stays the same for the defined period.
CDs commonly provide fixed rates.
Savings accounts usually have variable rates.
If you want certainty about the yield for a specific term and do not need immediate access to the funds, a CD may be worth considering.
How the Federal Reserve Can Affect Your Savings
The federal-funds rate influences borrowing and saving conditions throughout the economy.
When the Fed raises rates, banks often increase deposit rates, although the changes vary.
When the Fed lowers rates, savings Apes can also decline.
In September 2026, the Federal Reserve raised its target range to 3.75%-4.00%.
This demonstrates why the rate environment can change even during a single calendar year.
How Inflation and Fed Policy Affect HYSAs
Inflation and monetary policy can influence savings-account rates.
When inflation is elevated, central banks may maintain or raise interest rates to bring price growth down.
Higher benchmark rates can make it easier for banks to offer higher savings yields.
However, banks do not have to pass changes through equally or immediately.
Your bank’s PAY is determined by its own pricing decisions.
How Often Should You Recheck Your Rate?
A reasonable approach is to review it every few months.
You do not have to move your money every time another bank advertises a slightly higher rate.
Instead, check:
- Your current PAY
- New market-leading rates
- Fees
- Requirements
- Changes in account terms
If your account is substantially less competitive than available alternatives, consider switching.
How to Find the Current Best HAYS Rates
Use multiple sources.
Compare:
- Bank rate
- NerdWallet
- Major banking websites
- Official bank pages
- Credit-union websites
Third-party comparison sites can help identify competitive accounts, but the financial institution’s own website should be used to verify the actual PAY and account terms before opening the account.
This is particularly important because rates can change.
Why You Should Verify Rates Directly With the Bank
A comparison article can be accurate when published but become outdated later.
Savings rates are variable.
A bank can change its PAY after a comparison page is written.
Always look for the bank’s official current rate page.
Check the “as of” date whenever available.
What “Rate Last Updated” Means
A strong financial article should clearly distinguish between:
- Publication date
- Research date
- Rate verification date
This is particularly important for HAYS content because rates can change quickly.
For a website article, consider adding a short note such as:
“Apes last verified October 1, 2026. Rates may change.”
That makes the article more transparent.
Common Mistakes When Choosing a HAYS
Mistake 1: Choosing a Rate Without Reading Conditions
The highest PAY may require direct deposit or other criteria.
Mistake 2: Ignoring Fees
A monthly fee reduces interest earnings.
Mistake 3: Ignoring Balance Limits
A high rate may apply only to a small portion of your balance.
Mistake 4: Assuming the Rate Is Fixed
Most HYSAs are variable.
Mistake 5: Ignoring Deposit Insurance
Verify FDIC or NCUA coverage.
Mistake 6: Choosing an Account Without Checking Access
If emergencies are possible, easy transfers matter.
Mistake 7: Chasing Tiny Rate Differences
Moving $10,000 for a 0.05% difference may not be worthwhile.
Mistake 8: Keeping All Cash in One Place
For large balances, insurance limits matter.
How to Optimize a HAYS
Start by choosing a competitive account.
Then automate your savings.
Avoid fees.
Review the PAY periodically.
Keep enough checking cash for near-term bills.
Do not unnecessarily withdraw from savings.
Maintain emergency liquidity.
If the balance becomes very large, review deposit insurance.
A Simple Monthly Savings Plan
Suppose you earn $5,000 after taxes each month.
You might decide to save 10%.
That would be $500 per month.
After one year, your contributions would total $6,000.
If your HAYS pays interest during that time, your balance could exceed the contribution amount.
The exact result depends on timing and PAY changes.
The important part is that the savings habit becomes automatic.
How to Increase Your Savings Rate
Increasing your savings rate can be more powerful than changing banks constantly.
You can increase savings by:
- Reducing unnecessary subscriptions
- Negotiating bills
- Cooking at home
- Automating transfers
- Saving bonuses
- Saving tax refunds
- Saving part of raises
- Setting spending limits
Every additional $100 saved per month adds $1,200 per year before interest.
What to Do With a Tax Refund
A tax refund can be used in several ways.
You might:
- Build an emergency fund
- Pay high-interest debt
- Fund a short-term goal
- Contribute to retirement
- Add to a home fund
If you are still building emergency savings, a HAYS can be a practical place to hold those funds.
What to Do With a Work Bonus
A work bonus can be divided between spending, debt reduction, savings, and long-term investments.
Putting a portion into a HAYS can increase your emergency reserve.
The right split depends on your broader financial priorities.
Can a HAYS Replace an Emergency Fund?
It can be the account where you hold the emergency fund.
But the emergency fund itself is a financial reserve, not a bank product.
The important characteristics are:
- Enough money
- Easy access
- Stability
- Low risk
- Appropriate insurance
A HAYS can satisfy many of those requirements.
How Much Should Be in Checking vs Savings?
There is no universal percentage.
A practical approach is to keep enough money in checking for upcoming bills and routine spending, while moving the rest of your short-term reserve to savings.
For example:
Checking = one month of expected spending
HAYS = emergency fund and larger short-term goals
The exact amount depends on your cash-flow schedule.
Can You Use a HAYS for Recurring Expenses?
Yes.
Some people use a HAYS to save for predictable annual expenses such as:
- Car insurance
- Property taxes
- Holiday spending
- Membership renewals
- School expenses
- Annual subscriptions
You can divide the expected yearly bill by 12 and transfer that amount every month.
Sinking Funds and HYSAs
A sinking fund is money saved gradually for a predictable future expense.
For example, if your car insurance costs $1,200 every year, you can save $100 per month.
Keeping that money in a HAYS allows you to earn interest while gradually building the amount.
This approach can make large annual bills easier to handle.
What If Your Bank Offers a Lower Rate Than Competitors?
Check whether the difference is meaningful.
Suppose your current rate is 3.90% and the top alternative is 4.10%.
On $5,000, the annual difference is about $10.
That may not justify switching.
On $100,000, the difference would be approximately $200 per year.
Now the decision becomes more meaningful.
The Role of Convenience
Convenience has financial value.
A bank with slightly higher PAY may not be worth using if:
- Transfers are difficult
- Customer service is poor
- The app is unreliable
- Account requirements are complicated
- You cannot easily access money
A slightly lower rate can be acceptable if the overall banking experience works better for you.
How to Compare Three Accounts
Imagine:
Account A: 4.50% PAY, balance cap
Account B: 4.20% PAY, direct deposit required
Account C: 4.00% PAY, no requirements
If you have $3,000 and can satisfy Account B’s requirement, B may be attractive.
If you have $25,000 and Account A caps the top rate at $5,000, you should calculate the blended return.
If you want maximum simplicity, Account C may be easier to manage.
This illustrates why there is no universal best account.
Best HAYS for Emergency Funds
The strongest characteristics for an emergency fund are generally:
- FDIC insurance
- Easy access
- No unnecessary fees
- Competitive PAY
- Reliable transfers
- Strong account security
Do not sacrifice emergency access solely to earn a slightly higher yield.
Best HAYS for a Down Payment
For a home down payment, consider:
- PAY
- Balance limits
- Transfer speed
- FDIC insurance
- Withdrawal accessibility
If you expect to buy within a year, liquidity may matter more than maximizing every fraction of a percentage point.
Best HAYS for Large Savings
For larger balances, focus more heavily on:
- Effective PAY
- Balance caps
- Deposit insurance
- Fees
- Ownership category
- Customer service
A high rate on only the first few thousand dollars may not be useful for a six-figure balance.
Best HAYS for Beginners
Beginners may want:
- No monthly fee
- No minimum balance
- No complicated requirements
- Easy transfers
- FDIC insurance
- A simple mobile app
The simplest account is often easier to maintain.
Best HAYS for Frequent Savers
If you deposit money every paycheck, consider an account with:
- Automatic transfers
- High PAY
- No monthly fee
- Goal tracking
- Easy external transfers
Automation can make saving almost effortless.
Best HAYS for Couples
Couples may benefit from a joint savings account for shared expenses.
Possible goals include:
- Emergency fund
- House
- Car
- Vacation
- Household repairs
Before opening a joint account, understand the ownership terms and applicable deposit insurance.
Best HAYS for Families
Families may want separate savings goals for different expenses.
For example:
Emergency Fund
Education
Vacation
Home Repairs
Medical
Annual Bills
A bank that provides savings buckets can simplify organization.
Best HAYS for Freelancers
Freelancers should consider accounts that allow them to separate business reserves from personal spending.
A HAYS can help hold:
- Tax money
- Emergency reserves
- Equipment savings
- Business cash
However, personal and business finances should generally be kept properly separated where appropriate.
How to Open a HAYS
Opening an account usually requires basic identifying information.
You may need:
- Full name
- Social Security number
- Date of birth
- Address
- Government-issued ID
- Existing bank information
You may also need to complete identity verification.
Once the account is approved, you can transfer money into it.
What to Do After Opening the Account
Do not stop at the opening process.
Set up:
- Automatic deposits
- Account alerts
- Security features
- Savings goals
- Beneficiary information where applicable
Then monitor the account periodically.
When You Should Keep Your Existing Bank
You may not need to change banks if:
- Your current PAY is competitive
- Fees are low
- Transfers are easy
- Customer service is strong
- You value branch access
- The account fits your financial goals
The purpose of comparison is not necessarily to move money.
It is to know whether your current setup remains competitive.
When You Should Consider Changing Accounts
A switch may be worth considering when:
- Your PAY becomes much lower than the market
- The bank introduces fees
- Requirements become inconvenient
- Customer service deteriorates
- The account is no longer competitive
- You find materially better terms elsewhere
Before switching, verify the new account carefully.
How to Transfer Your Savings Safely
First, open and verify the new account.
Then link your existing checking account if necessary.
Start with a small transfer if you are unfamiliar with the process.
Confirm that the funds arrived.
Then transfer the remaining amount.
Do not close the old account until you verify that all automatic transfers and important payments have been redirected.
Security During Account Transfers
Before transferring money:
- Confirm the bank’s official website
- Verify routing numbers
- Use secure login
- Avoid public computers
- Enable multi-factor authentication
- Confirm recipient details
Fraudulent banking websites can look convincing.
What to Look for in Account Terms
Review the disclosures for:
- PAY
- Interest calculation
- Interest crediting frequency
- Fees
- Minimum balance
- Transfer limits
- Withdrawal policies
- Account closure policies
- Insurance
- Eligibility
The fine print often contains the information that matters most.
How Interest Is Credited
Some banks calculate interest daily and credit it monthly.
Others use different schedules.
The exact method can vary.
The PAY is generally the most useful number for comparing accounts because it accounts for compounding effects.
What Happens if You Withdraw Money?
Your balance decreases.
Future interest calculations will be based on the lower balance.
If you withdraw frequently, your annual interest earnings may be lower.
This is another reason to use a HAYS primarily for savings rather than everyday spending.
Should You Use a HAYS for an Investment Opportunity?
If you are holding money temporarily before making a long-term investment, a HAYS can provide a place to keep the cash while you decide what to do.
But investment decisions should consider:
- Risk
- Time horizon
- Diversification
- Liquidity
- Tax consequences
Do not treat the HAYS itself as an investment strategy for every goal.
How HYSAs Fit Into a Financial Plan
A financial plan might contain several layers.
Daily spending: Checking account
Emergency savings: HAYS
Short-term goals: HAYS or CDs
Medium-term goals: Savings, CDs, bonds, or other suitable assets
Long-term goals: Diversified investments
This approach recognizes that different dollars have different jobs.
The Importance of Time Horizon
Your time horizon is one of the most important factors in choosing where to keep money.
Money needed next month should generally be treated differently from money needed in 20 years.
Short horizon → prioritize access and stability.
Long horizon → consider growth and inflation.
A HAYS is particularly useful for the first category.
Why a High PAY Can Still Be Misleading
Suppose a bank advertises 5%.
That sounds excellent.
But the rate could:
- Apply only for three months
- Require a large deposit
- Be limited to a low balance
- Require direct deposit
- Drop to 1% afterward
Another bank paying 4% indefinitely may create a better long-term result.
Always compare the complete time period.
A Better Way to Compare Promotional Offers
Calculate expected earnings during the promotional period.
Then calculate expected earnings after the promotion.
For example:
First six months: 5%
Next six months: 2%
That is very different from:
12 months: 4%
Do not compare only the highest advertised number.
What Should You Ask Before Opening a HAYS?
Ask:
What is the current PAY?
Is it variable?
Does the PAY require direct deposit?
Is there a balance cap?
Is there a minimum balance?
Are there monthly fees?
Is the bank FDIC-insured?
How quickly can I transfer money?
Are there withdrawal limits?
Can I access Tams?
What happens if the PAY changes?
Getting answers to these questions can prevent unpleasant surprises.
Final Checklist Before Opening a High-Yield Savings Account
Before depositing your money, verify:
PAY: Competitive and clearly stated.
Fees: Understand all recurring and transaction charges.
Minimums: Know the opening and ongoing balance requirements.
Conditions: Identify direct-deposit or monthly-deposit requirements.
Balance Caps: Determine how much of your money receives the advertised rate.
Insurance: Verify FDIC or NCUA coverage.
Access: Review transfers, Tams, branches, and mobile banking.
Security: Enable multi-factor authentication.
Taxes: Understand that savings interest is generally taxable.
Rate Changes: Remember that most HAYS Apes are variable.
Best High-Yield Savings Accounts: Final Takeaway
The best high-yield savings accounts can help Americans earn significantly more interest on their cash than low-yield traditional savings accounts.
As of late September 2026, competitive HYSAs are offering rates around 4% or higher, while selected products advertise still higher yields under specific conditions. Recent market comparisons include Happen Bank and Western State Bank at 4.20% PAY, CIT Bank at 4.10%, Viol Bank at 4.01%, and Live Oak Bank at 4.00%, while some conditional offers have reached 4.50%.
The important thing is not simply finding the largest number.
Instead, evaluate the entire account.
A good high-yield savings account should provide a combination of:
- Competitive PAY
- Low or no monthly fees
- Appropriate minimum-balance requirements
- Convenient transfers
- Strong digital banking
- Reliable customer service
- Deposit insurance
- Clear terms
- Suitable access to your money
For many people, the emergency fund is the most obvious place to use a HAYS.
A strong emergency fund can provide financial flexibility when unexpected expenses arise.
The account can also be useful for short-term goals such as a house down payment, car purchase, vacation, taxes, education costs, or business reserves.
At the same time, a savings account should not automatically be treated as a replacement for long-term investing.
Money that you will need soon generally has different priorities from money intended for retirement decades into the future.
The Federal Reserve’s interest-rate decisions can also influence the savings environment. In September 2026, the Fed increased the federal-funds target range to 3.75% to 4.00%, illustrating why bank deposit rates can shift as the broader rate environment changes.
Because high-yield savings rates are usually variable, the account with the highest PAY today may not remain the highest-paying option later.
That does not mean you should constantly move your money.
Instead, review your account periodically.
Ask whether your PAY remains competitive.
Check whether your bank has introduced new fees.
Review your account requirements.
Confirm that your savings remain insured within applicable limits.
And consider whether your account still matches the purpose of your money.
For large balances, deposit insurance becomes particularly important. The FDIC’s standard coverage is $250,000 per depositor, per insured bank, for each ownership category, so consumers with balances near or above that level should pay close attention to how deposits are structured.
Ultimately, the strongest savings strategy is often simple.
Save consistently.
Automate contributions.
Keep emergency money accessible.
Avoid unnecessary fees.
Choose a competitive interest rate.
Understand the account terms.
Review your rate from time to time.
And give every dollar a clear purpose.
A high-yield savings account will not make you wealthy overnight, but it can help your cash work harder while preserving the accessibility that many short-term financial goals require.
For someone who currently keeps a large amount of money in a traditional low-interest savings account, comparing competitive HYSAs may be one of the easiest ways to potentially increase interest income without taking the market risk associated with stocks or other investments.
Before opening an account, verify the current PAY, fees, minimum balance, eligibility requirements, rate conditions, withdrawal rules, and FDIC or NCUA insurance directly with the financial institution. Savings rates can change, and a comparison published today may not reflect the rate available several weeks or months later.
The right high-yield savings account is therefore not simply the account displaying the biggest PAY.
It is the account whose rate, safety, accessibility, fees, requirements, and features fit your financial goals.
That is the approach most likely to make your savings strategy practical, sustainable, and useful over time.
For more information about this critical Click Here
For more information about this Click Here